The State of REITs: October 2026 Edition
-
- September (-6.45%) was an even tougher month for REITs than August (-4.48%).
- Micro caps (-12.11%) had a particularly ugly total return in September. Small cap REITs (-4.65%) weathered the storm the least badly followed by mid caps (-6.17%) and large caps (-6.47%).
- Only 13.79% of REITs posted a positive total return in September, but 66.46% remain in the black year-to-date.
- 100% of REIT property types averaged negative returns in September, with Timber (-13.51%) and Infrastructure (-10.65%) seeing the sharpest drops. Hotels (-1.80%) and Land (-2.41%) were the best performers.
- The average REIT NAV continued to widen during September from -13.20% to -17.78%. The median NAV discount also widened from -15.13% to -19.63%.
REIT Performance
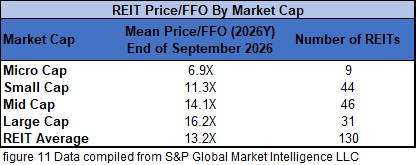
The REIT sector fell for the 3rd straight month in September with a -6.54% average total return. REITs again underperformed the NASDAQ (+1.9%), S&P 500 (-0.3%) and Dow Jones Industrial Average (-4.1%). The market cap weighted Vanguard Real Estate ETF (VNQ) outperformed the average REIT in September (-6.24% vs. -6.54%) and has also narrowly outpaced the average REIT year-to-date (+4.19% vs. +3.83%). The spread between the 2026 FFO multiples of large cap (16.2x) and small cap REITs (11.3x) narrowed in September as multiples contracted 1.3 turns for large caps and only 0.6 turns for small caps. Investors currently need to pay an average of 43.4% more for each dollar of FFO from large cap REITs relative to small cap REITs. In this monthly publication, I will provide REIT data on numerous metrics to help readers identify which property types and individual securities currently offer the best opportunities to achieve their investment goals.
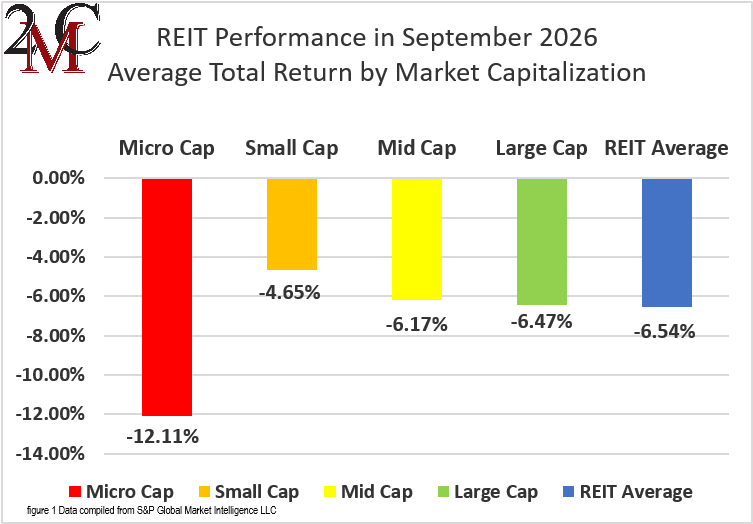
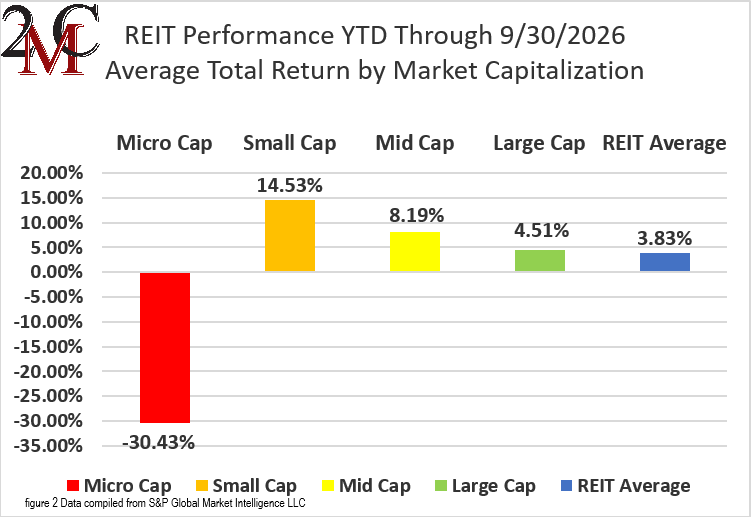
Micro cap REITs (-12.11%) yet again badly underperformed in September. Small caps (-4.65%) averaged a more modest negative return followed by mid caps (-6.17%) and large caps (-6.54%). During the first nine months of 2026, small cap REITs have outperformed large caps by 1002 basis points.
18 out of 18 Property Types Averaged Negative Returns in September
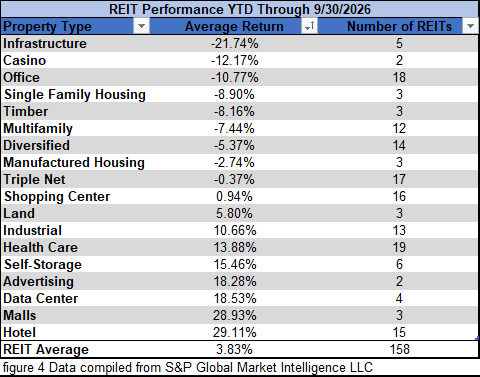
100% of REIT property types averaged a negative total return in September with an 11.71% total return spread between the best and worst-performing property types. Hotels (-1.80%) and Land (-2.41%) were the best performers in the REIT sector, while Timber (-13.51%), Infrastructure (-10.65%) and Diversified (-10.36%) all averaged double-digit negative returns.
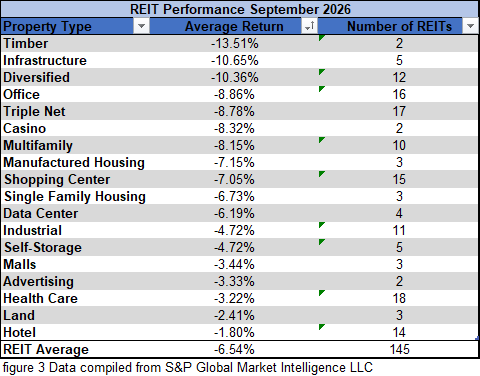
Over the first nine months of 2026, Infrastructure (-21.74%), Casinos (-12.17%) and Office (-10.77%) averaged double-digit negative returns. Hotels (+29.11%) and Malls (+28.93%) have had the strongest average returns among REIT property types thus far in 2026.
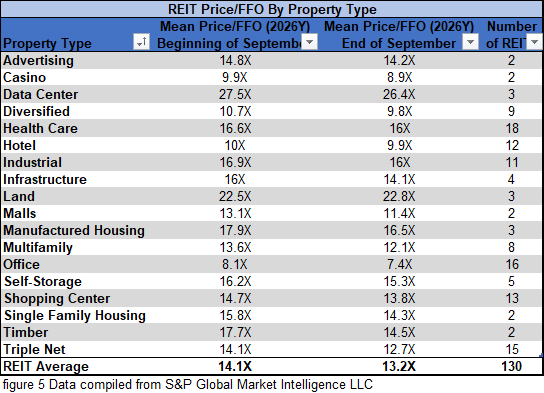
The REIT sector as a whole saw the average P/FFO (2026Y) decrease from 14.1x to 13.2x during September. Only 5.6% of property types averaged multiple expansion while the remaining 94.4% averaged multiple contraction. Data Centers (26.4x), Land (22.8x) and Manufactured Housing (16.5x) currently trade at the highest average multiples among REIT property types. The property types with the lowest FFO multiples are Office (7.4x), Casinos (7.9x), Diversified (9.8x) and Hotels (9.9x).
Performance of Individual Securities
Site Centers (SITC) (+14.24%) bucked the negative REIT trend in September with a double-digit gain. SITC is in the process of liquidating all assets and distributing proceeds to shareholders, which presents a very different kind of opportunity than that of most other REITs.
Wheeler REIT (WHLR) (-46.90%) continues to be the worst-performing REIT almost every single month as the share price continues to freefall. In just the first 9 months of 2026, WHLR has had a nearly total wipeout of shareholders with a -99.97% return. To put that in perspective, $100 of Wheeler stock at the start of the year is worth just 3 cents a mere nine months later.
86.21% of REITs had a negative total return in September. Despite back-to-back months of decline, REITs have averaged +3.83% year-to-date total return in 2026, which is more than 500 basis points better than the -1.74% return for the REIT sector over the same period in 2025.
Dividend Yield
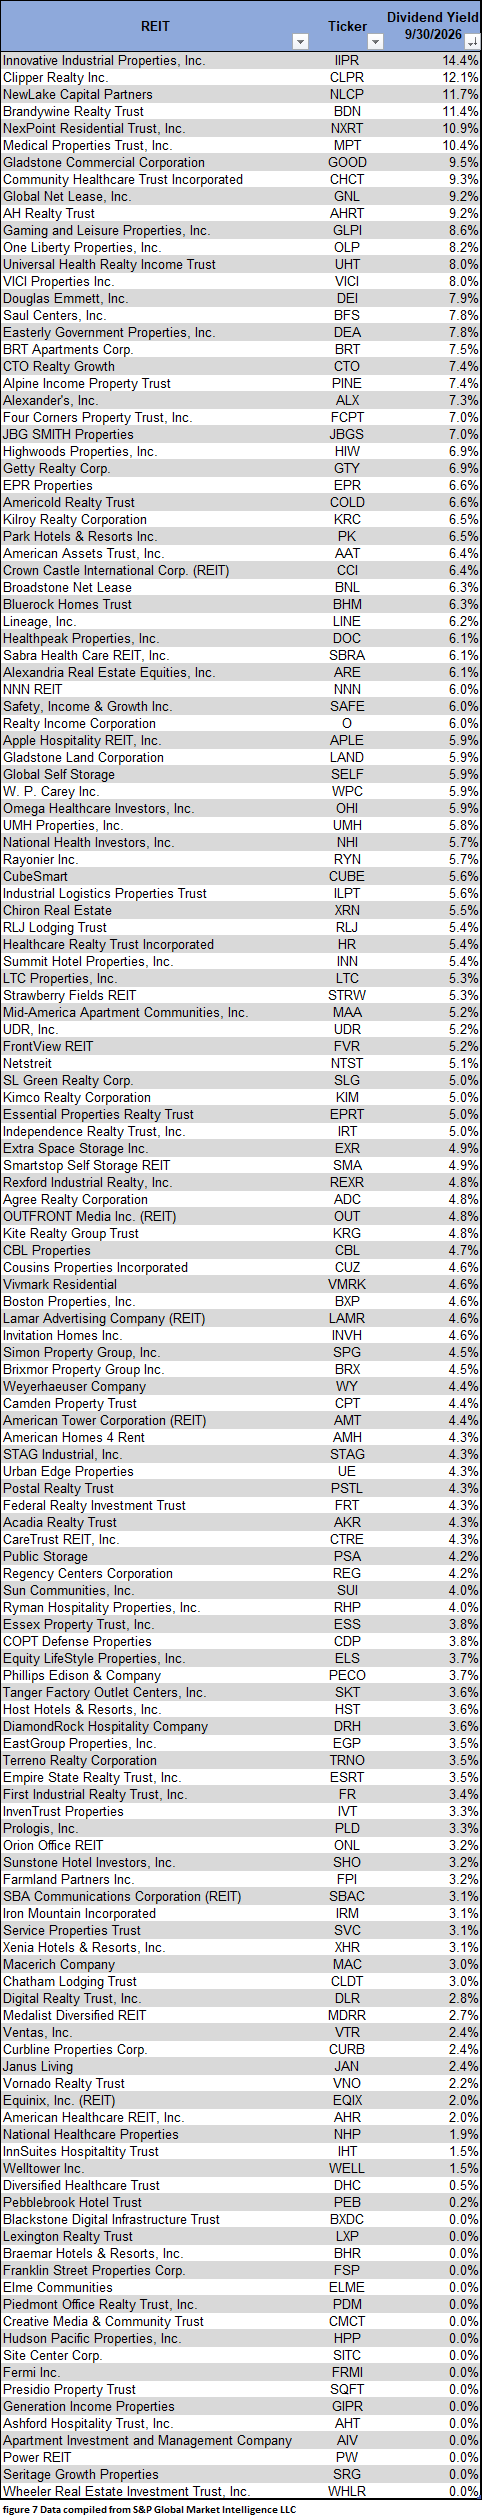
Dividend yield is an important component of a REIT’s total return. The particularly high dividend yields of the REIT sector are, for many investors, the primary reason for investment in this sector. As many REITs are currently trading at share prices well below their NAV, yields are currently quite high for many REITs within the sector. Although a particularly high yield for a REIT may sometimes reflect a disproportionately high risk, there exist opportunities in some cases to capitalize on dividend yields that are sufficiently attractive to justify the underlying risks of the investment. I have included below a table ranking equity REITs from highest dividend yield (as of 9/30/2026) to lowest dividend yield.
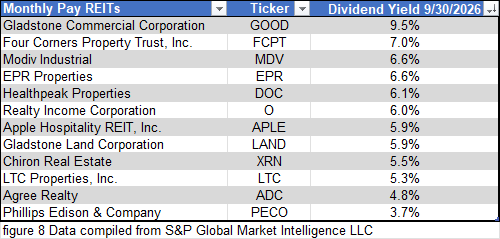
Although a REIT’s decision to pay a quarterly or monthly dividend does not reflect the quality of the company’s fundamentals or operations, a monthly dividend provides smoother cash flow for investors. Below is a list of equity REITs that pay monthly dividends, ranked from highest yield to lowest yield.
Dividend News
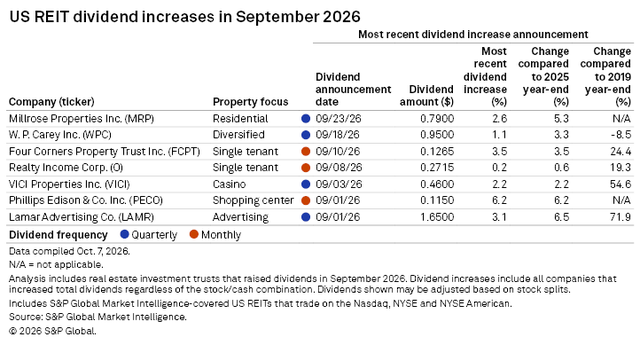
7 REITs announced dividend increases in September of which 4 pay quarterly and 3 pay monthly. Over the first three quarters of 2026, 55 REITs have increased their dividends. Phillips Edison & Co. (PECO) had the biggest dividend hike in September at +6.2%. This was followed by smaller increases from Four Corners Properties Trust (FCPT) (+3.5%), Lamar Advertising (LAMR) (+3.1%), Millrose Properties (MRP) (+2.6%) and VICI Properties (VICI) (+2.2%).
Valuation
REIT Premium/Discount to NAV by Property Type
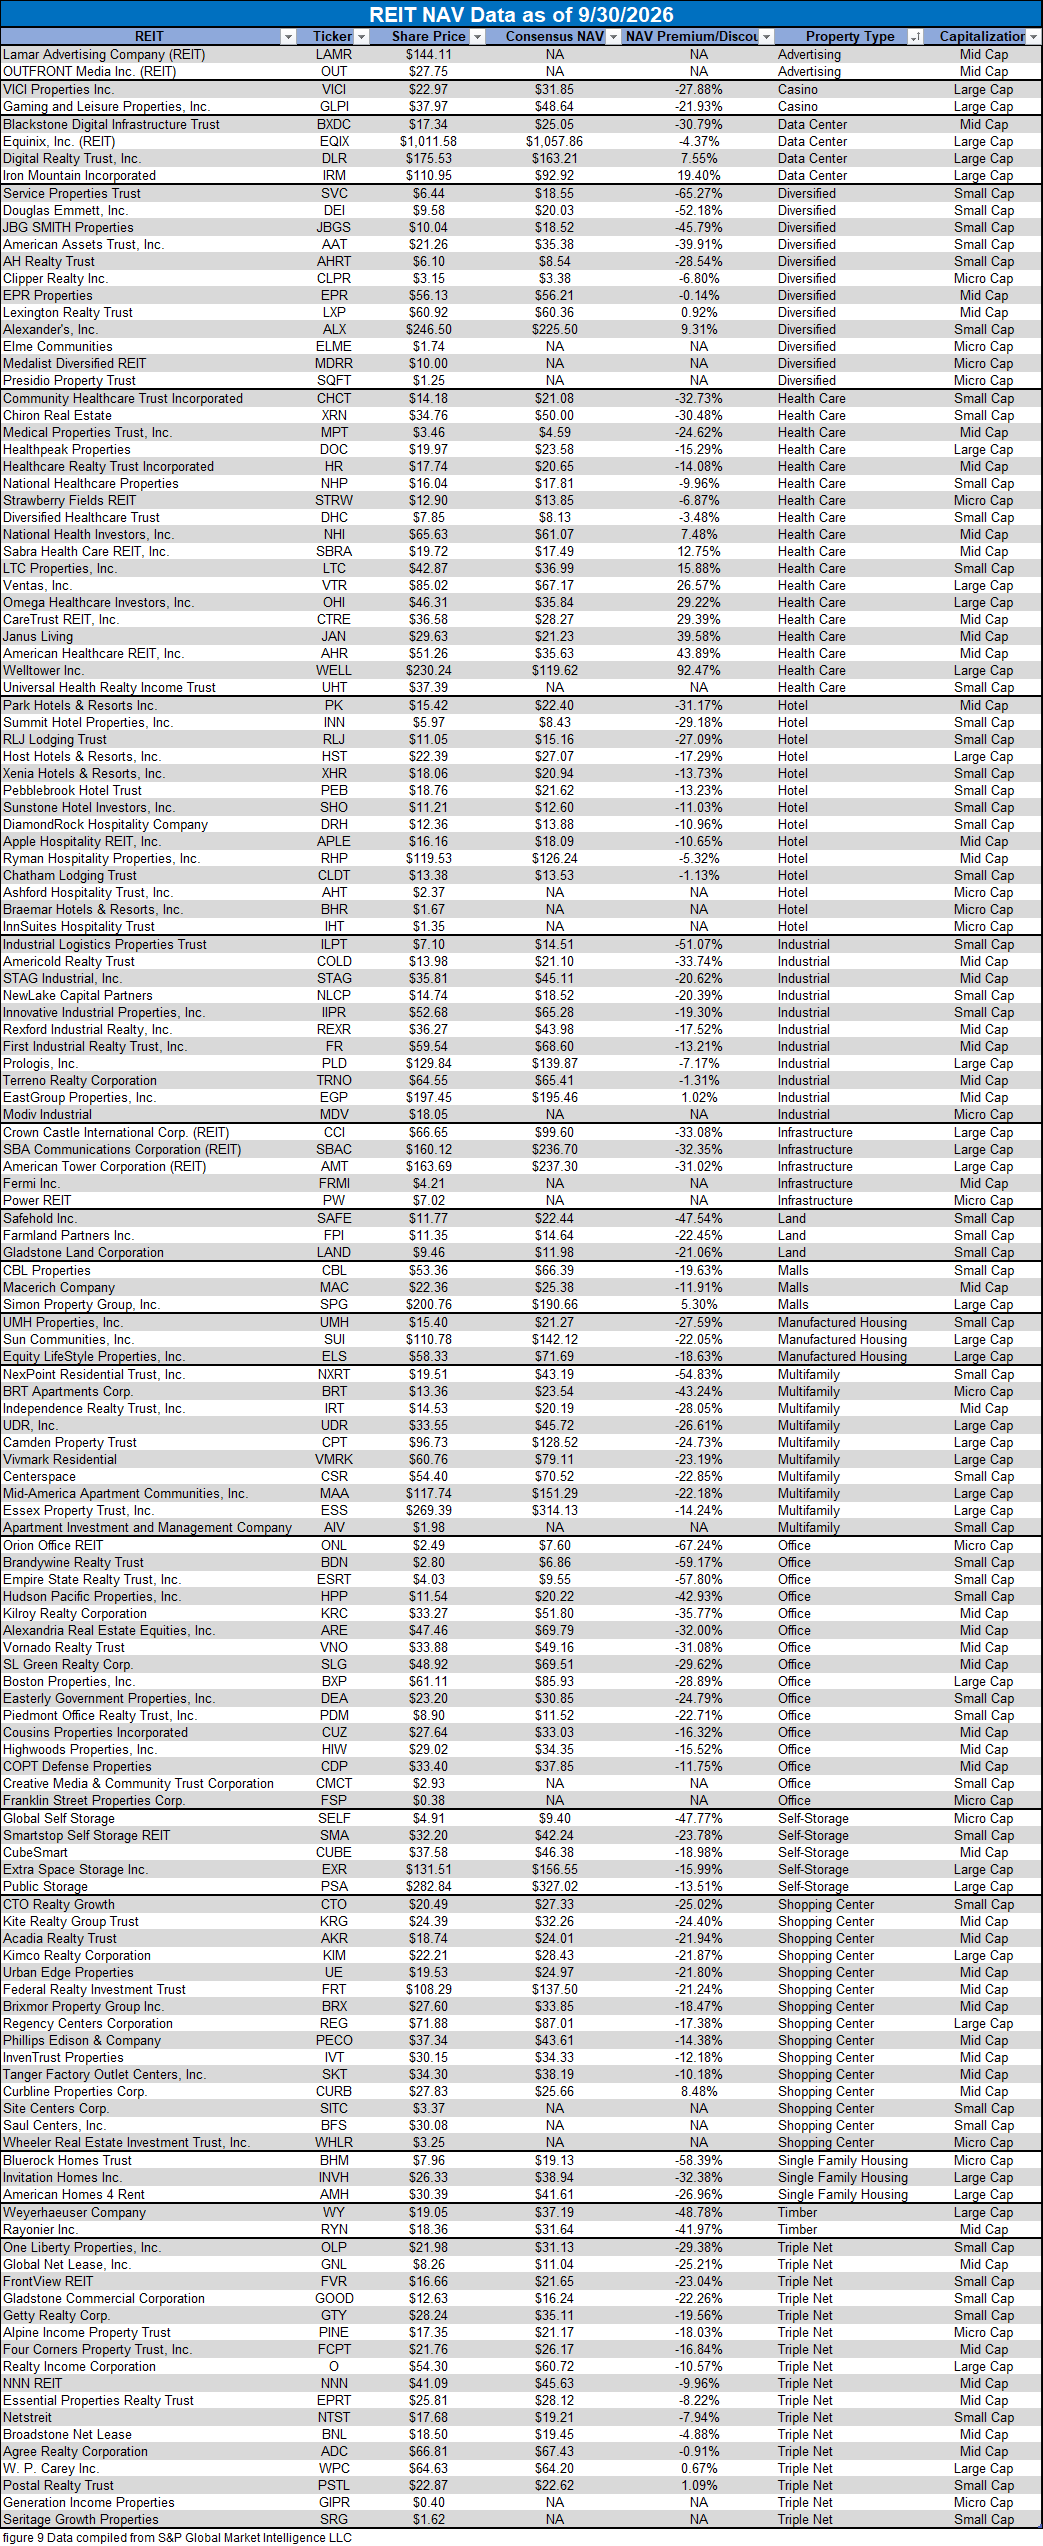
Below is a downloadable data table, which ranks REITs within each property type from the largest discount to the largest premium to NAV. The consensus NAV used for this table is the average of analyst NAV estimates for each REIT. Both the NAV and the share price will change over time, so I will continue to include this table in upcoming issues of The State of REITs with updated consensus NAV estimates for each REIT for which such an estimate is available.
Takeaway
The large cap REIT premium (relative to small cap REITs) narrowed in September, and investors are now paying, on average, about 43% more for each dollar of 2026 FFO/share to buy large cap REITs than small cap REITs (16.2x/11.3x – 1 = 43.4%). As can be seen in the table below, there is presently a strong positive correlation between market cap and FFO multiple.
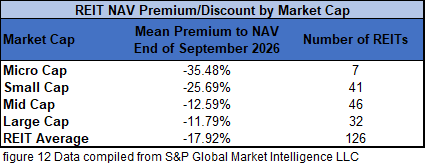
The table below shows the average NAV premium/discount of REITs of each market cap bucket. This data, much like the data for price/FFO, shows a strong, positive correlation between market cap and Price/NAV. The average large cap (-11.79%) and mid cap REITs (-12.59%) trade at low double-digit discounts to NAV. Small cap REITs (-25.69%) trade at about 3/4 of NAV while micro caps (-35.48%) trade for less than 2/3 of NAV.
The REIT Sector Overall Maintains Healthy Leverage Metrics, But a Divergence has Emerged Between Investment Grade and Non-Investment Grade REITs
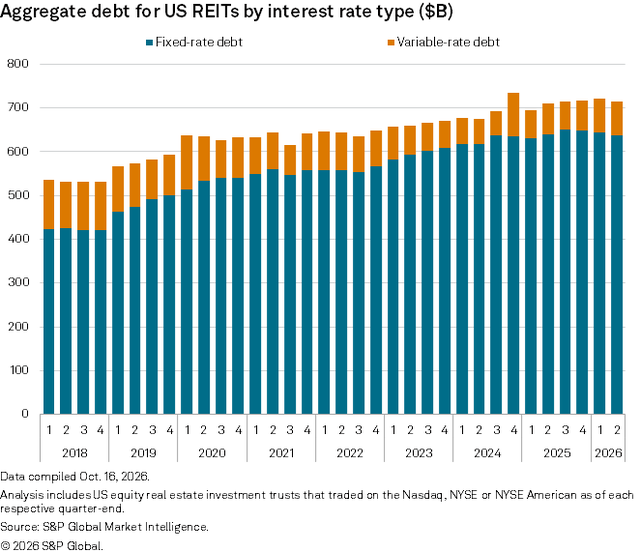
Over recent years, there has been a slow and steady increase in the total amount of debt held by REITs. Rising interest rates won’t impact most of this debt right away, however, due to the fact that 89.4% of REIT debt is fixed-rate. Only the 10.6% floating rate debt and any newly issued debt will face immediate impact from the recent interest rate spike.
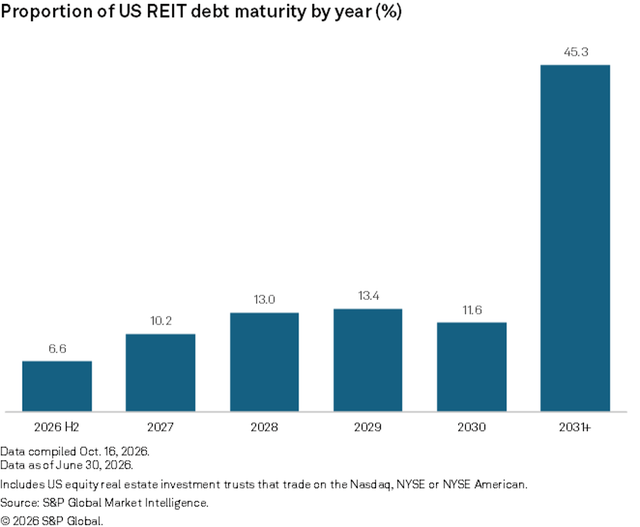
The majority of REIT debt does not mature until 2030 or later with only 6.6% scheduled to mature in 2026, 10.2% in 2027 and 13% in 2028. Any longer-dated fixed-rate debt won’t need to be refinanced at higher rates until farther into the future.
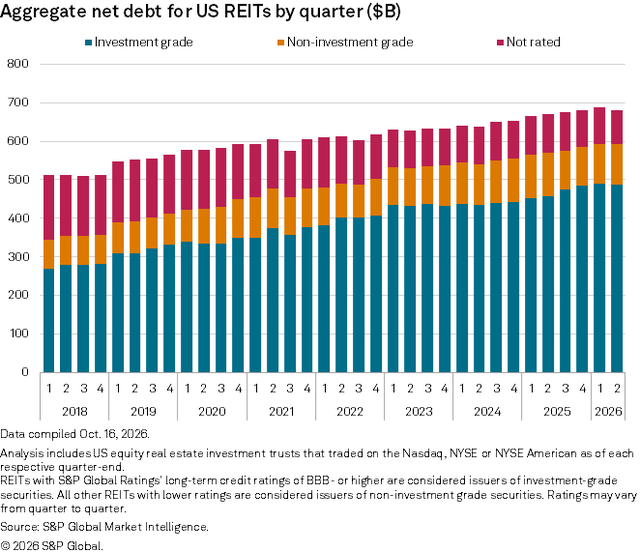
As of the end of the 2nd quarter of 2026, REITs in total held net debt of $680.55 billion. Most of this debt is held by REITs with investment grade credit ratings ($487.75 billion). $103.65 billion of net debt is held by REITs with a non-investment-grade credit rating and $89.14 billion is held by REITs that are not currently rated by S&P Global Ratings.
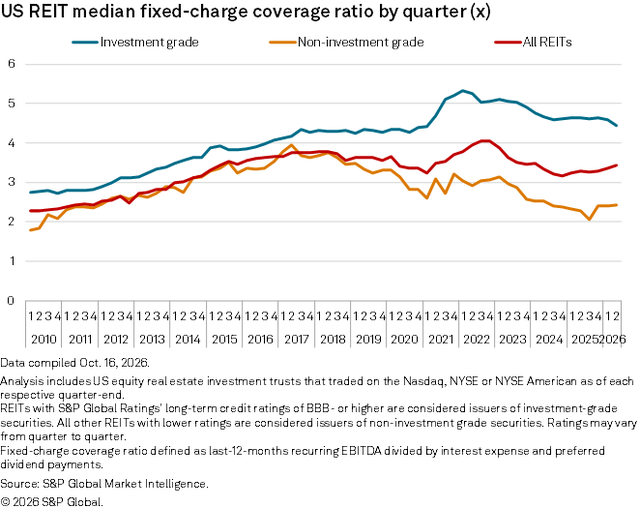
The REIT sector ended the 2nd quarter with a median fixed-charge coverage ratio of 3.3x. Although investment grade REITs have historically maintained a higher median fixed-charge coverage ratio than non-investment grade REITs, that spread has widened substantially. Investment grade REITs have a median fixed-charge coverage ratio of 4.5x which far exceeds the 2.4x median for REITs with non-investment grade ratings.
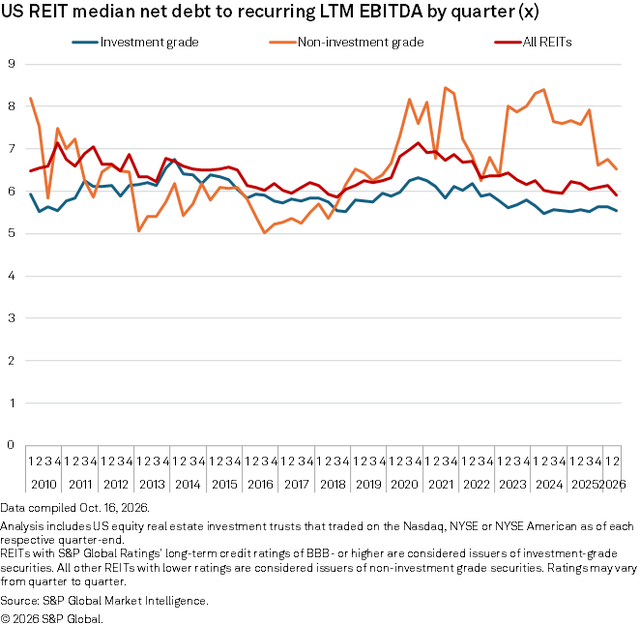
Prior to the pandemic, non-investment grade REITs actually often had lower median net debt to recurring LTM EBITDA than investment grade REITs. However, that sharply flipped and investment grade REITs now consistently have a lower ratio. With better fixed-charge coverage ratios and lower median net debt to EBITDA, non-investment grade REITs carry a far different risk profile than their investment grade peers. In a rising interest rate environment, these debt metrics play a big role in whether investors value a REIT at a premium or discount to NAV.
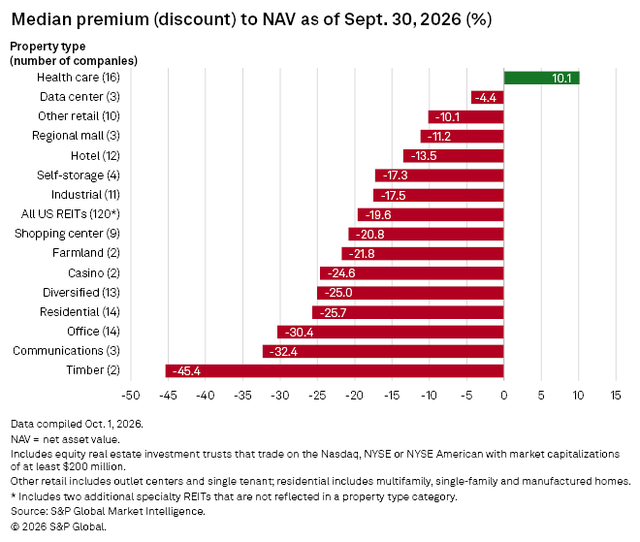
After the recent REIT selloff, Health Care (+10.1%) is the only REIT property type that remains above NAV. Average discounts by property type range from -4.4% (Data Centers) to -45.4% (Timber). All but two property types now average a double-digit discount to NAV.
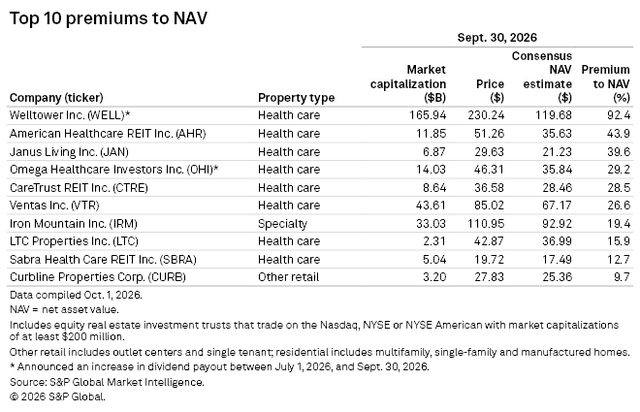
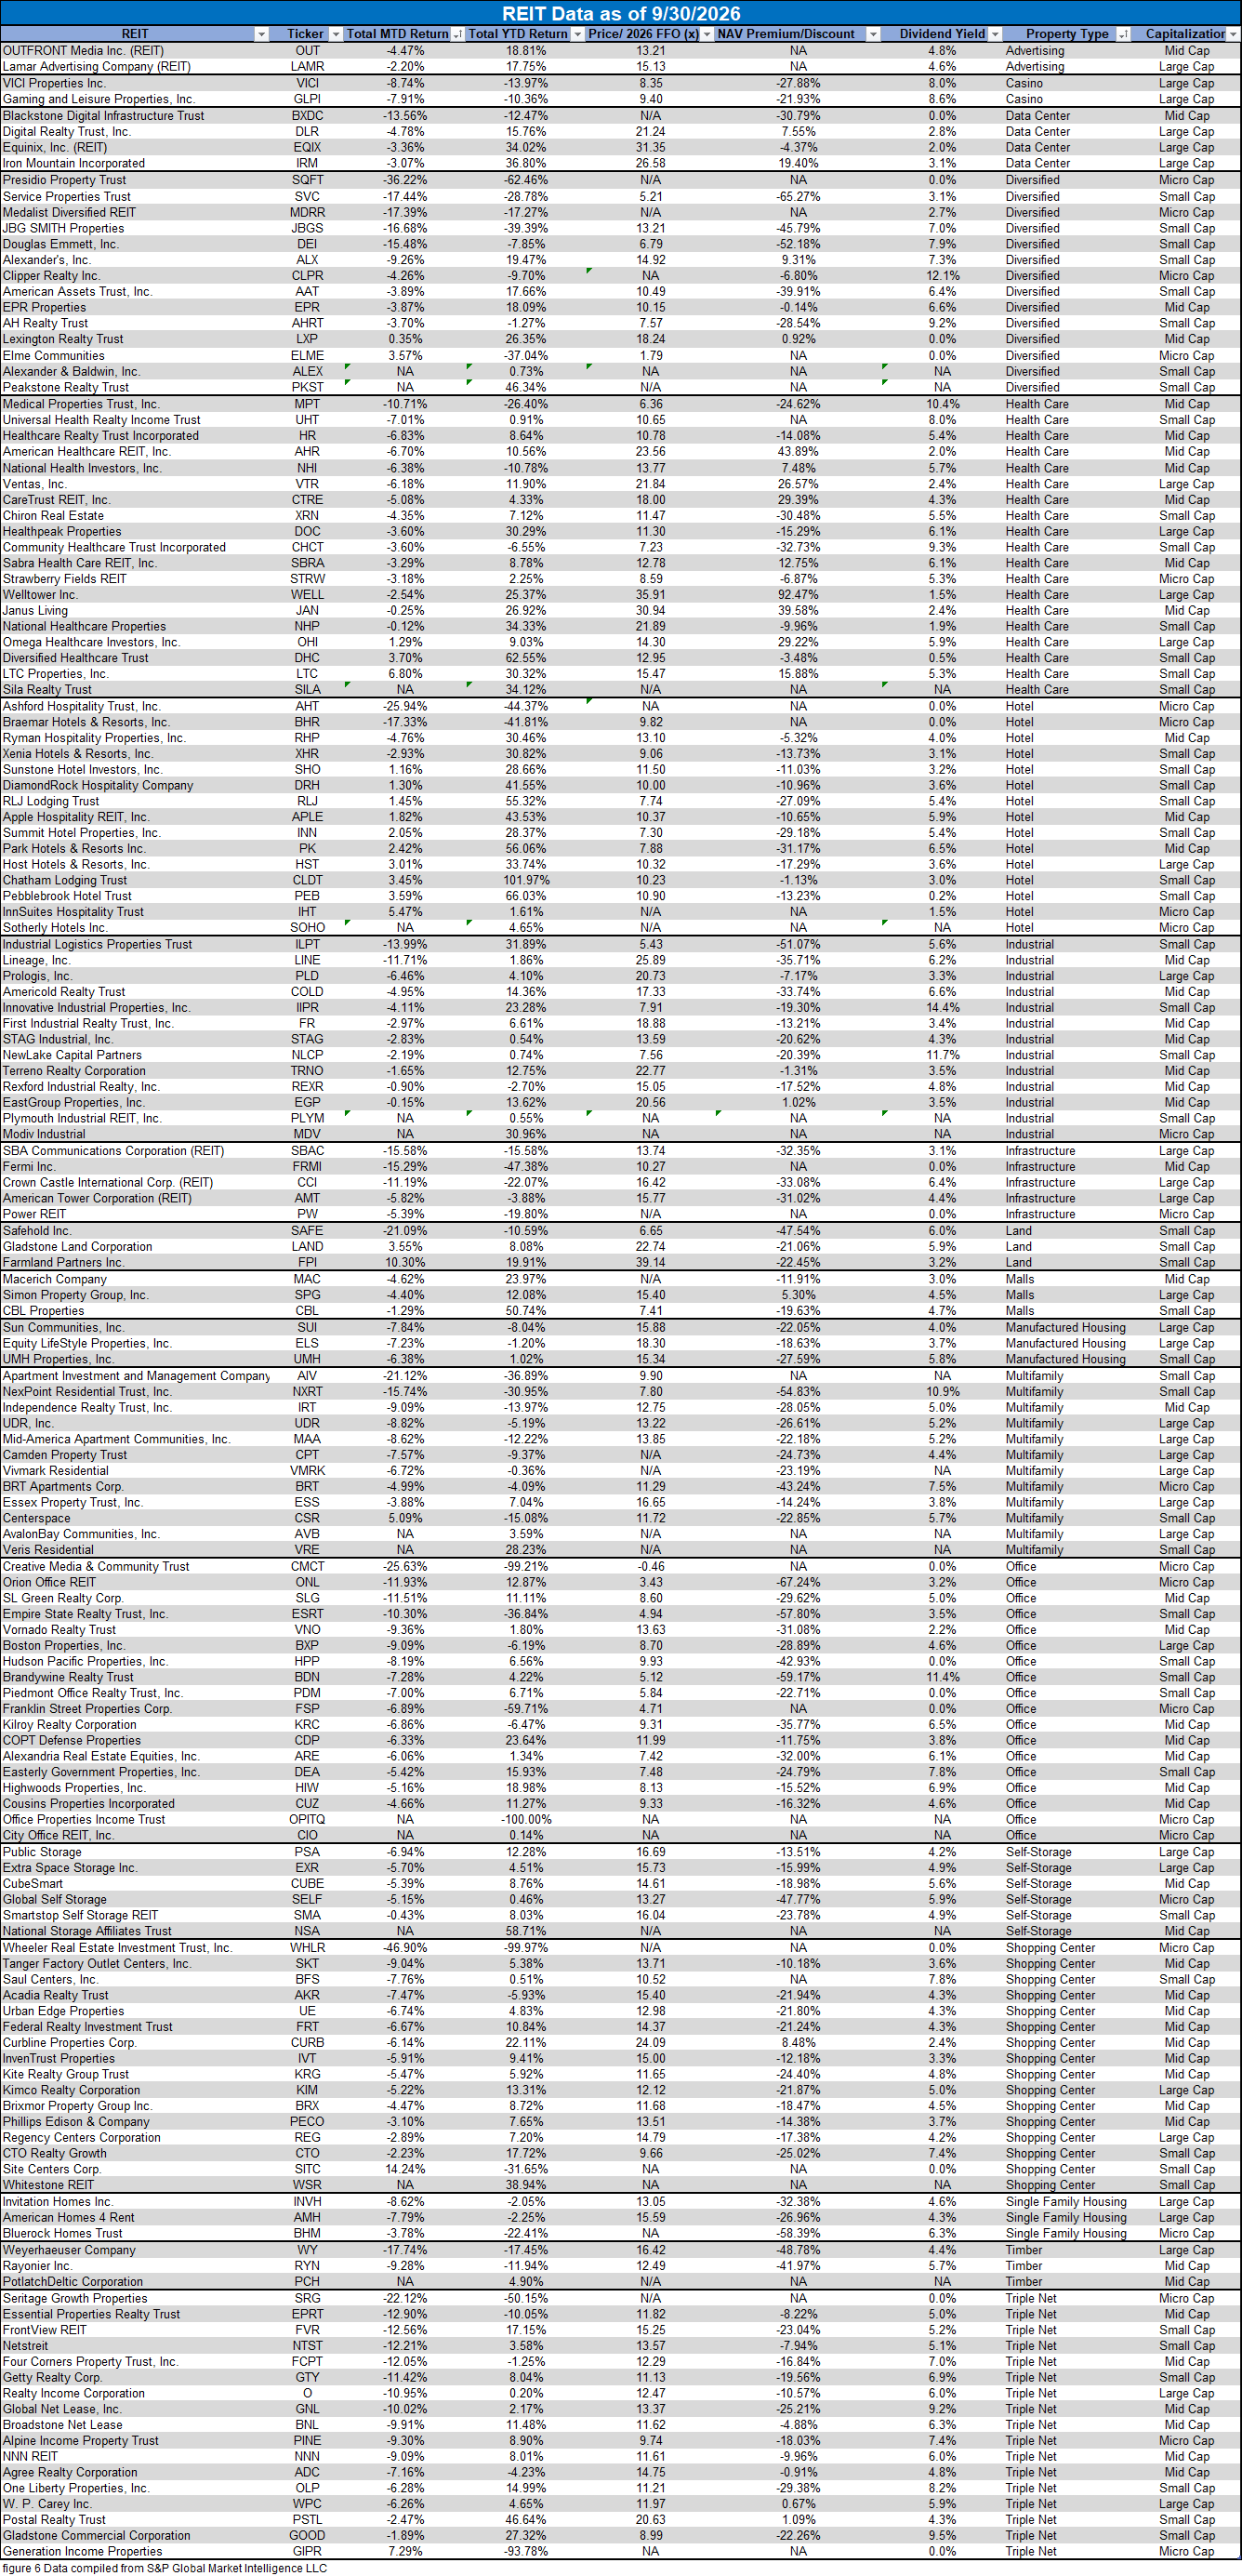
Health care dominates the list of REITs trading at the largest premiums to NAV, accounting for the 6 largest premiums and 8 of the top 10. The widest premium by far belongs to Welltower (WELL) (+92.4%) followed by fellow senior housing REITs American Healthcare REIT (AHR) (+43.9%) and Janus Living (JAN) (+39.6%). The lack of new senior housing construction coupled with strong and growing demand driven by favorable demographics, has created a highly lucrative environment for many senior housing landlords.
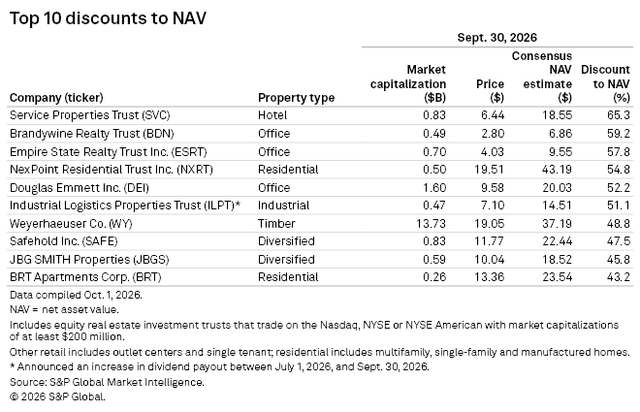
As can be seen in the table above, the vast majority of severely discounted REITs have a market cap less than $1B. There is a notable exception to this, however, in that large cap Weyerhaeuser (WY) is trading at an uncharacteristic 48.8% discount to NAV. Although Timber REITs are navigating a challenging environment (reduced construction volume, tariffs, high interest rates, etc.), a discount of this magnitude is still far beyond that of any other large cap REITs. The next deepest discounts among large caps are Crown Castle International (CCI) (-33.08%), Invitation Homes (INVH) (-32.38%), SBA Communications (SBAC) (-32.35%) and American Tower (AMT) (-31.02%). With very large discounts available throughout the sector, investors now have the opportunity to conduct their due diligence on a large pool of discounted REITs across many property types and market caps to identify which REITs have the greatest total return potential.
Important Notes and Disclosure
All articles are published and provided as an information source for investors capable of making their own investment decisions. None of the information offered should be construed to be advice or a recommendation that any particular security, portfolio of securities, transaction, or investment strategy is suitable for any specific person. The information offered is impersonal and not tailored to the investment needs of any specific person.
We cannot determine whether the content of any article or recommendation is appropriate for any specific person. Readers should contact their financial professional to discuss the suitability of any of the strategies or holdings before implementation in their portfolio. Research and information are provided for informational purposes only and are not intended for trading purposes. NEVER make an investment decision based solely on the information provided in our articles.
We may hold, purchase, or sell positions in securities mentioned in our articles and will not disclose this information to subscribers, nor the time the positions in the securities were acquired. We may liquidate shares in profiled companies at any time without notice. We may also take positions inconsistent with the information and views expressed on our website.
We routinely own and trade the same securities purchased or sold for advisory clients of 2MCAC. This circumstance is communicated to our clients on an ongoing basis. As fiduciaries, we prioritize our clients’ interests above those of our corporate and personal accounts to avoid conflict and adverse selection in trading these commonly held interests.
Past performance does not guarantee future results. Investing in publicly held securities is speculative and involves risk, including the possible loss of principal. Historical returns should not be used as the primary basis for investment decisions. Although the statements of fact and data in this report have been obtained from sources believed to be reliable, 2MCAC does not guarantee their accuracy and assumes no liability or responsibility for any omissions/errors
Commentary may contain forward-looking statements that are by definition uncertain. Actual results may differ materially from our forecasts or estimations, and 2MCAC and its affiliates cannot be held liable for the use of and reliance upon the opinions, estimates, forecasts, and findings in this article.
Through October 2021, The State of REITs was published exclusively on Seeking Alpha by Simon Bowler, Sector Analyst at 2nd Market Capital Services Corporation (2MCSC). Editions subsequent to October 2021 will be published on this website in addition to other platforms that may include Seeking Alpha. 2MCSC was formed in 1989 and provides investment research and consulting services to 2nd Market Capital Advisory Corporation. 2MCSC does not provide investment advice. 2MCSC is a separate entity but related under common ownership to 2nd Market Capital Advisory (2MCAC), a Wisconsin registered investment advisor. Simon Bowler is an investment advisor representative of 2MCAC. Any positive comments made by others should not be construed as an endorsement of the author's abilities to act as an investment advisor.
S&P disclosure: S&P Global Market Intelligence LLC. Contains copyrighted material distributed under license from S&P.
Discover more from 2nd Market Capital Advisory Corp
Subscribe to get the latest posts sent to your email.