The State of REITs: September 2026 Edition
- REITs had a very rough August with an average total return of -4.48%.
- Micro caps (-7.87%) and small caps (-4.80%) performed very badly in August. Large cap (-3.30%) and mid cap REITs (-3.52%) were also in the red, albeit with somewhat more modestly negative total returns.
- Only 17.69% of REIT securities had a positive total return in August, but 77.85% are in the black year-to-date.
- 89% of REIT property types averaged negative returns in August, with Shopping Centers (-11.34%) and Hotels (-7.74%) hit the hardest. Land (+5.82%) and Manufactured Housing (+2.08%) were the only property types in the black.
- The average REIT NAV significantly widened from -8.43% to -13.20% during August. The median NAV discount similarly widened from -9.44% to -15.13%.
REIT Performance
REITs have now declined in back-to-back months, with an average total return of -0.49% in July and -4.48% in August. In August, REITs badly underperformed the NASDAQ (+1.7%), S&P 500 (+2.0%), and Dow Jones Industrial Average (+3.4%). The market cap weighted Vanguard Real Estate ETF (VNQ) outperformed the average REIT in August (-2.54% vs. -4.48%) and has also exceeded the average REIT year-to-date (+11.13% vs. +9.67%). The spread between the 2026 FFO multiples of large cap (17.5x) and small cap REITs (11.9x) was unchanged in August as multiples contracted 0.4 turns for large caps and 0.4 turns for small caps. Investors currently need to pay an average of 47.1% more for each dollar of FFO from large cap REITs relative to small cap REITs. In this monthly publication, I will provide REIT data on numerous metrics to help readers identify which property types and individual securities currently offer the best opportunities to achieve their investment goals.
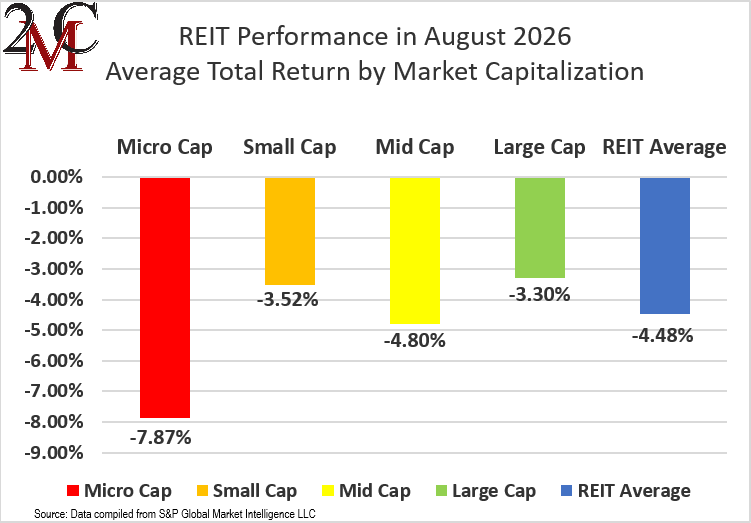
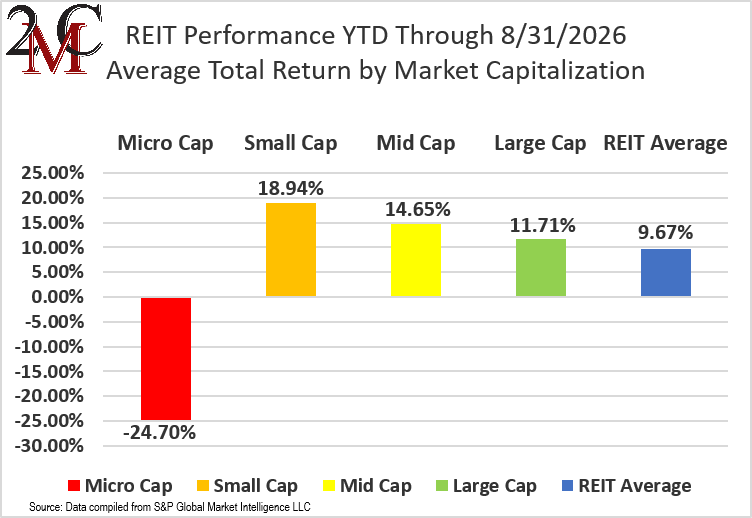
Micro-cap REITs (-7.87%) continued to underperform in August. Large caps (-3.30%), small caps (-3.52%), and mid caps (-4.80%) also finished the month in the red, albeit with smaller average declines. During the first eight months of 2026, small cap REITs have outperformed large caps by 723 basis points.
2 out of 18 Property Types Averaged Positive Returns in August
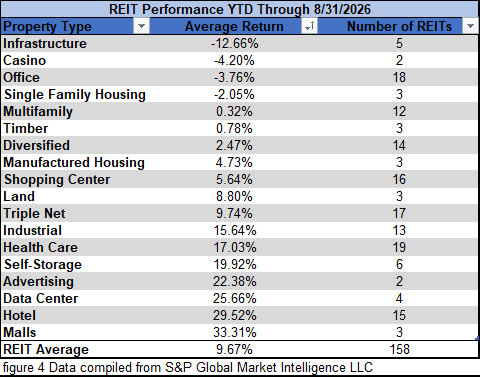
88.89% of REIT property types averaged a negative total return in August, with a 17.16% total return spread between the best and worst performing property types. Land (+5.82%) and Manufactured Housing (+2.08%) led the REIT sector, while Shopping Centers (-11.34%) and Hotels (-7.74%) saw heavy declines in August.
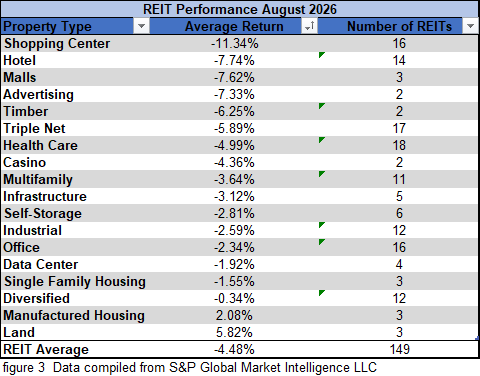
Over the first eight months of 2026, Infrastructure (-12.66%) and Casino (-4.20%) averaged the steepest losses. Malls (+33.31%) and Hotels (+29.52%) have outpaced all other REIT property types thus far in 2026.
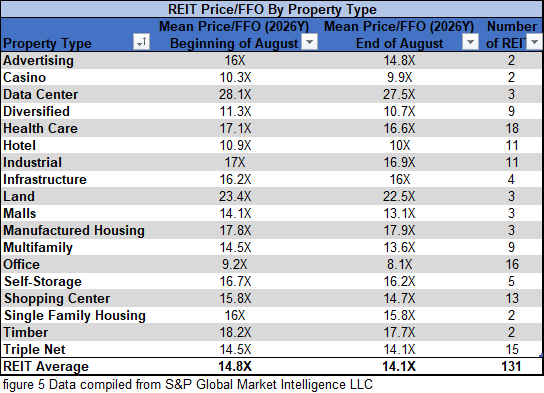
The REIT sector as a whole saw the average P/FFO (2026Y) decrease from 14.8x to 14.1x during August. Only 5.6% of property types averaged multiple expansion, while a whopping 94.4% averaged multiple contraction. Data Centers (27.5x), Land (22.5x), Manufactured Housing (17.8x), and Timber (17.7x) currently trade at the highest average multiples among REIT property types. The property types with the lowest FFO multiples are Office (8.1x), Casinos (9.9x), and Hotels (10x).
Performance of Individual Securities
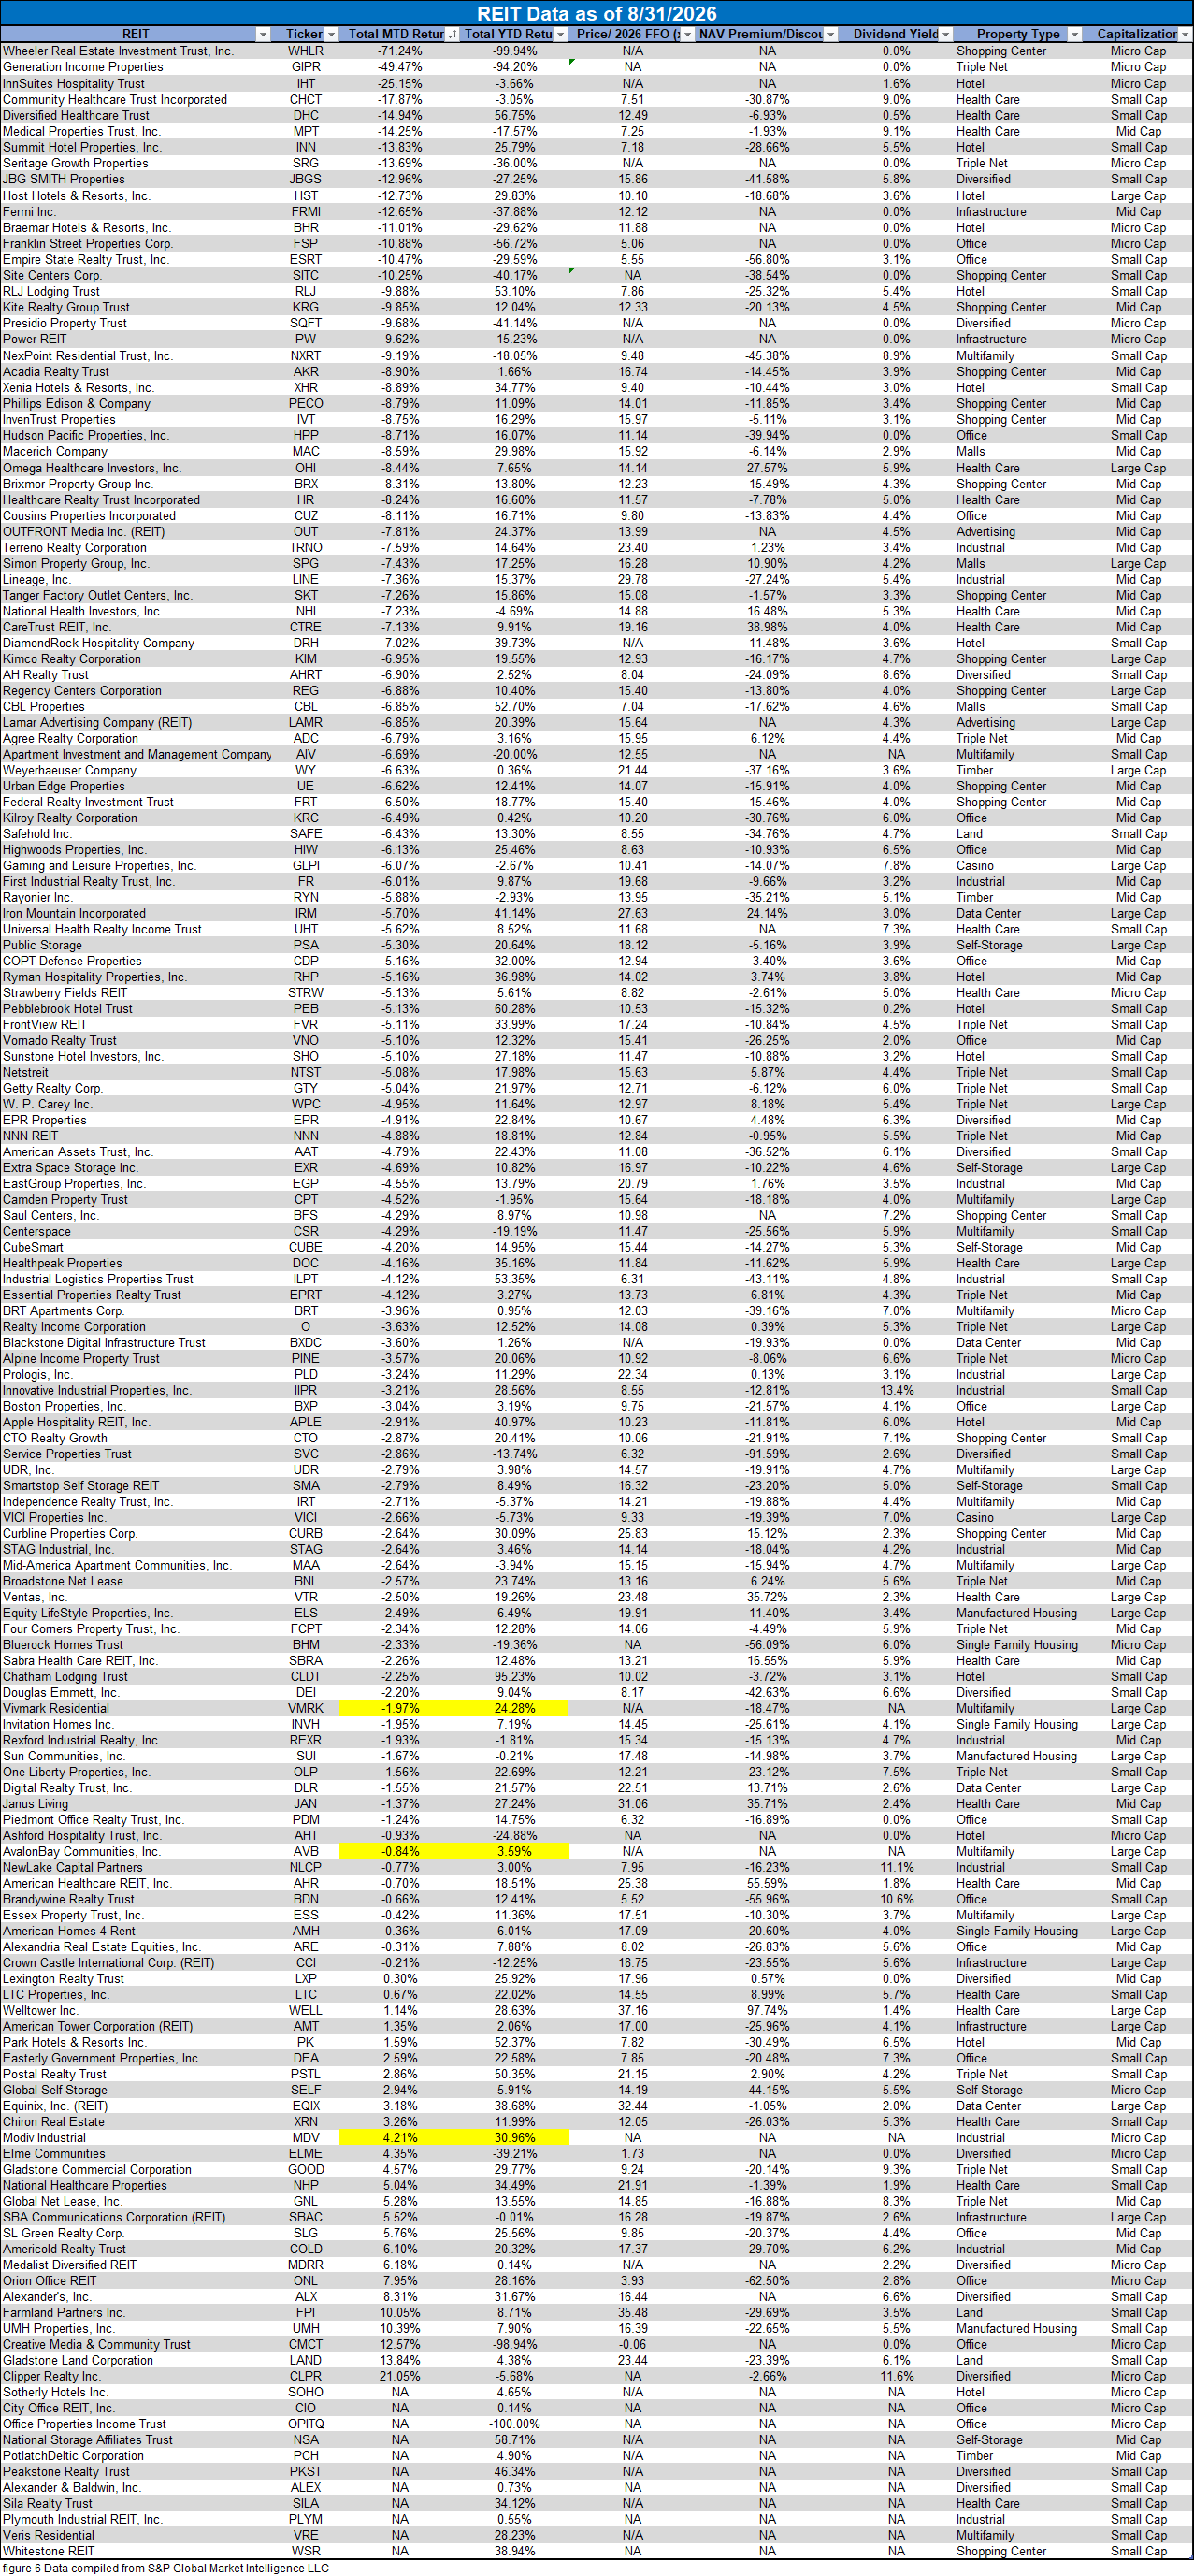
Modiv Industrial (MDV) was acquired by Global Net Lease (GNL) on August 12th in an all-stock transaction. Modiv shareholders received 1.975 shares of GNL for each share of MDV they owned.
Vivmark Residential (VMRK) formed on August 17th through the merger of Avalon Bay (AVB) and Equity Residential (EQR). Avalon Bay shareholders received 2.793 shares of EQR (now VMRK) for each share of AVB they owned. As both multifamily REITs were nearly equal in size, the combined entity’s ownership upon closing was composed of approximately 51.2% shares held by former AVB shareholders and 48.8% shares held by former EQR shareholders.
Clipper Realty (CLPR) (+21.05%) surged after posting Q2 earnings that exceeded expectations. Q2 AFFO/share of $0.09 blew past the consensus AFFO/share estimate of $0.03. Despite the strong August, Clipper remains in the red with a -5.68% total return over the first 8 months of the year.
Wheeler REIT (WHLR) (-71.24%) was the worst-performing REIT yet again in August as its collapse continues. Yet another horrific month has driven the year-to-date total return to a nearly complete shareholder wipeout of -99.94%.
82.31% of REITs had a negative total return in August. Despite the tough month, REITs have averaged a solid +9.67% year-to-date total return in 2026, which is more than 1000 basis points better than the -1.11% return for the REIT sector over the same period in 2025.
Dividend Yield
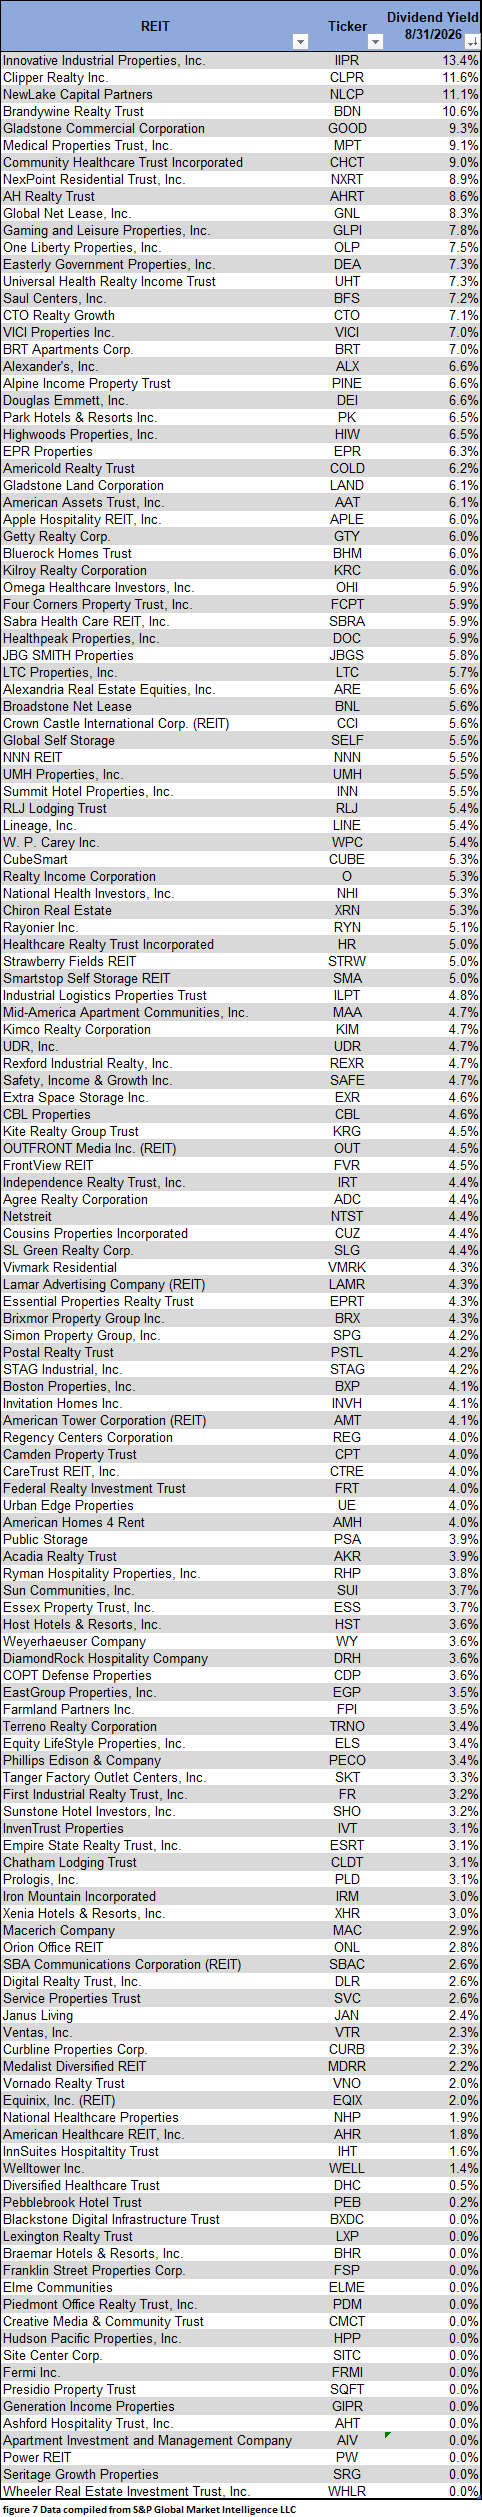
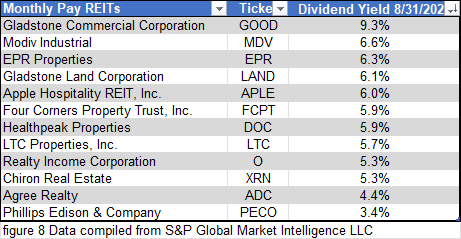
Dividend yield is an important component of a REIT’s total return. The particularly high dividend yields of the REIT sector are, for many investors, the primary reason for investment in this sector. As many REITs are currently trading at share prices well below their NAV, yields are currently quite high for many REITs within the sector. Although a particularly high yield for a REIT may sometimes reflect a disproportionately high risk, there exist opportunities in some cases to capitalize on dividend yields that are sufficiently attractive to justify the underlying risks of the investment. I have included below a table ranking equity REITs from highest dividend yield (as of 8/31/2026) to lowest dividend yield.
Although a REIT’s decision to pay a quarterly or monthly dividend does not reflect the quality of the company’s fundamentals or operations, a monthly dividend provides smoother cash flow for investors. Below is a list of equity REITs that pay monthly dividends, ranked from highest yield to lowest yield.
Dividend News
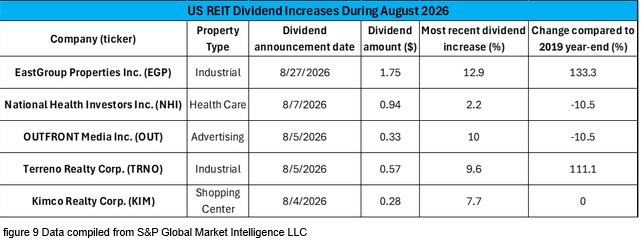
5 REITs announced dividend hikes in August, all of which pay quarterly. Over the first eight months of 2026, 51 REITs have increased their dividends. The most substantial dividend raise in August was the 12.9% hike from EastGroup Properties (EGP), followed by +10% from OUTFRONT Media (OUT) and +9.6% from Terreno Realty (TRNO). Kimco Realty (KIM) and National Health Investors (NHI) also announced dividend increases of 7.7% and 2.2%, respectively. Kimco’s dividend increase marks a return to the pre-COVID quarterly dividend of $0.28 that the Shopping Center REIT had before cutting it in 2020.
Valuation
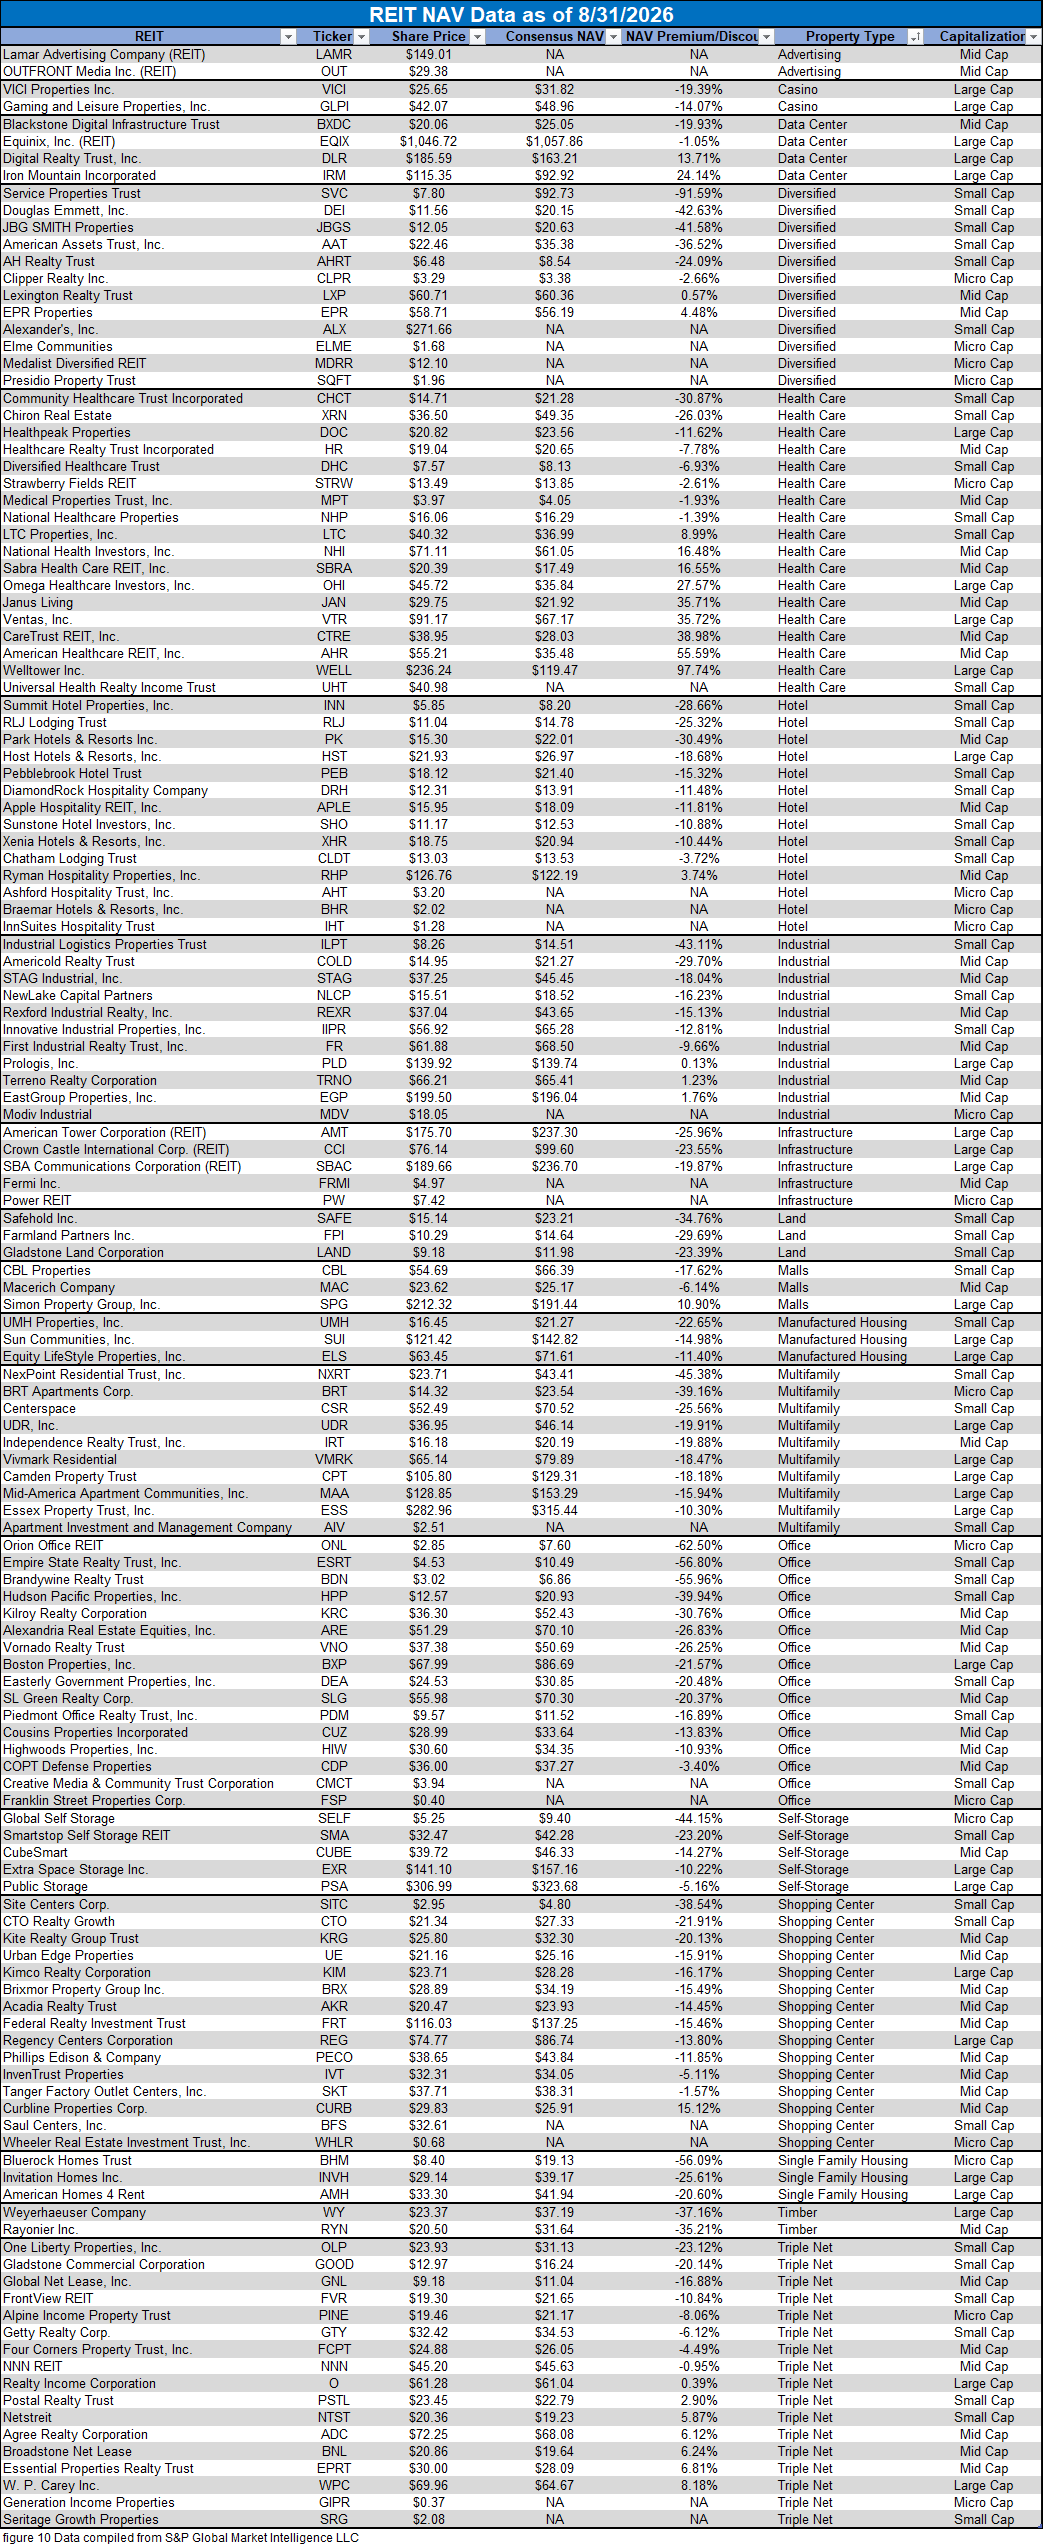
REIT Premium/Discount to NAV by Property Type
Below is a downloadable data table that ranks REITs within each property type from the largest discount to the largest premium to NAV. The consensus NAV used for this table is the average of analyst NAV estimates for each REIT. Both the NAV and the share price will change over time, so I will continue to include this table in upcoming issues of The State of REITs with updated consensus NAV estimates for each REIT for which such an estimate is available.
Takeaway
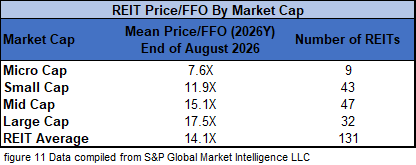
The large cap REIT premium (relative to small cap REITs) widened again in August, and investors are now paying, on average, about 47% more for each dollar of 2026 FFO/share to buy large cap REITs than small cap REITs (17.5x/11.9x – 1 = 47.1%). As can be seen in the table below, there is presently a strong positive correlation between market cap and FFO multiple.
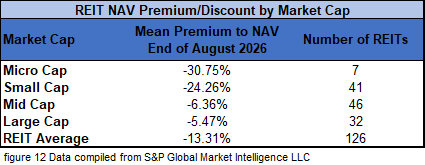
The table below shows the average NAV premium/discount of REITs of each market cap bucket. This data, much like the data for price/FFO, shows a strong, positive correlation between market cap and Price/NAV. The average large cap (-5.47%) and mid cap REITs (-6.36%) trade at mid-single-digit discounts to NAV. Small cap REITs (-24.26%) trade at about 3/4 of NAV while micro caps (-30.75%) trade for a little more than 2/3 of NAV.
REITs Continue to See Strong Same-Store NOI Growth and Are Capitalizing on High Implied Cap Rates with Accretive Share Repurchases
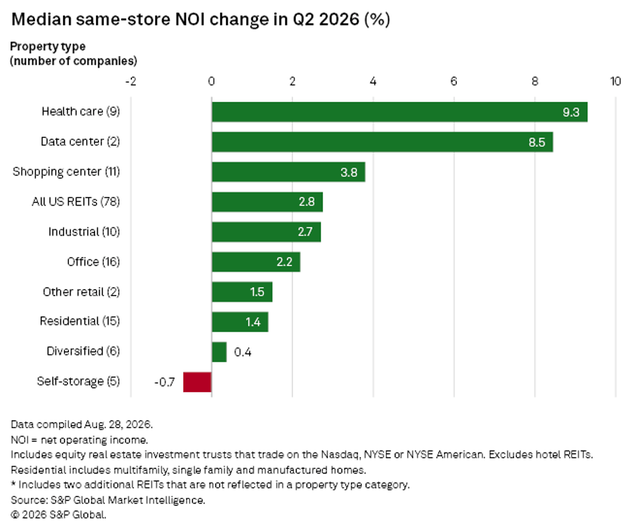
The REIT sector as a whole saw a median same-store NOI (SS-NOI) growth of +2.8% during the 2nd quarter of 2026. Although Self Storage REITs (-0.7%) saw negative SS-NOI growth in Q2, other property types saw positive growth ranging from +0.4% to +9.3%. Health Care (+9.3%) and Data Centers (+8.5%) far exceeded the SS-NOI growth of all other REIT property types.
The top 3 strongest Q2 SS-NOI growth REITs were all from the Health Care sector: Janus Living (JAN) (+16.5%), Welltower (WELL) (+15.5%), and American Healthcare REIT (AHR) (+13.2%). Other REITs that achieved double-digit SS-NOI growth were Office Properties Income Trust (OPI) (+11.9%), Ventas (+10.3%), and CTO Realty Growth (CTO) (+10.1%).
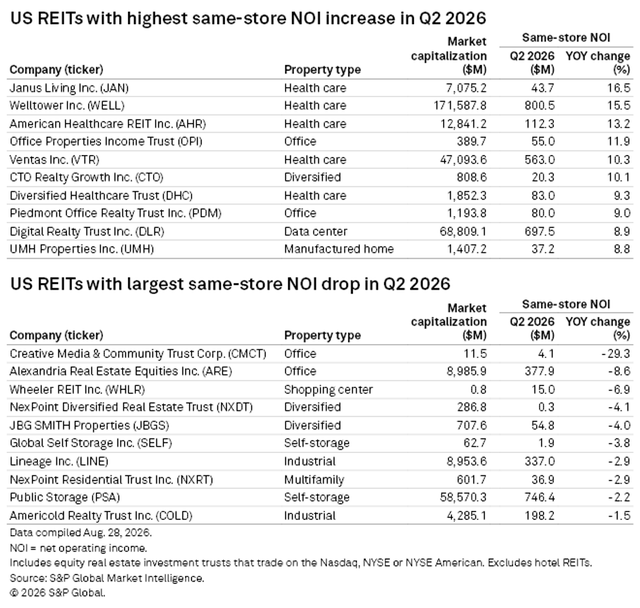
There was far more variance when it comes to the biggest SS-NOI declines in Q2, with no more than 2 REITs from any property type represented on the list. The sharpest year-over-year SS-NOI declines came from Creative Media & Community Trust (CMCT) (-29.3%), Alexandria Real Estate Equities (ARE) (-8.6%), and Wheeler REIT (WHLR) (-6.9%).
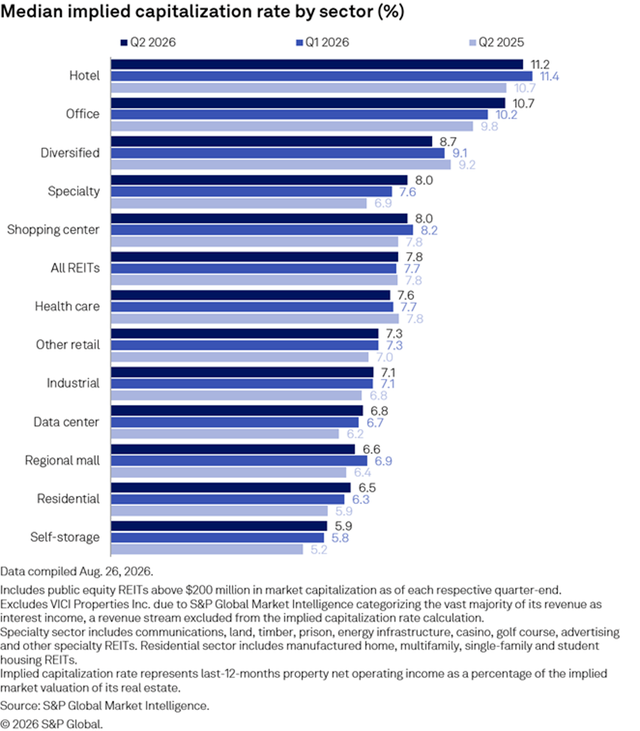
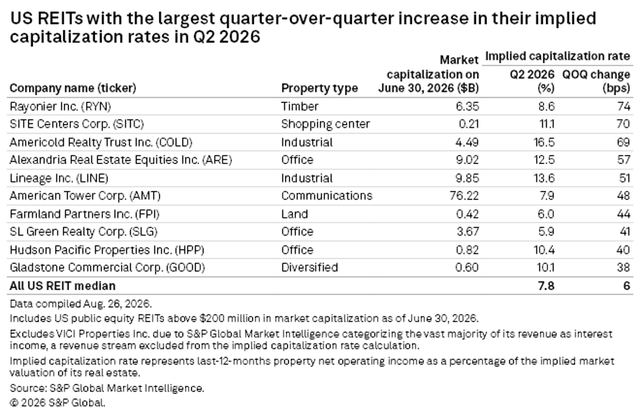
REIT implied cap rates for most property types remain elevated relative to private market cap rates, with the median REIT implied cap rate ticking up from 7.7% at the end of Q1 to 7.8% at the end of Q2. Hotels (11.2%) and Office (10.7%) median implied cap rates remain in double digits. Specialty REITs saw the biggest cap rate expansion during the quarter (+50 bps) and year-over-year (+110 bps). Diversified REITs saw the most cap rate compression (-40 bps) during Q2 and year-over-year (-50 bps).
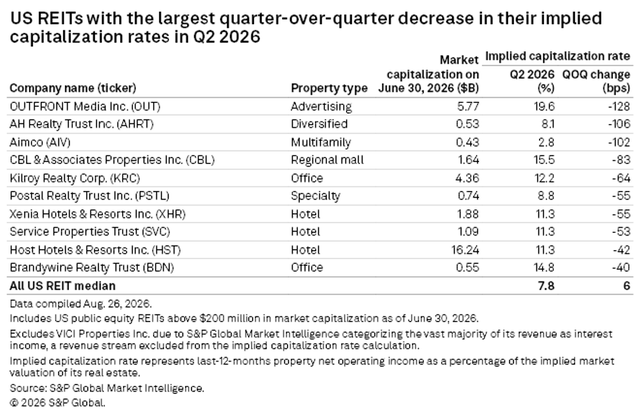
3 REITs saw cap rate compression greater than 100 bps during Q2: OUTFRONT Media (OUT) (-128 bps), AH Realty Trust (AHRT) (-106 bps), and Aimco (AIV) (-102 bps). A trio of Hotel REITs also saw strong implied cap rate compression: Xenia Hotels & Resorts (XHR) (-55 bps), Service Properties Trust (SVC) (-53 bps), and Host Hotels & Resorts (-42 bps).
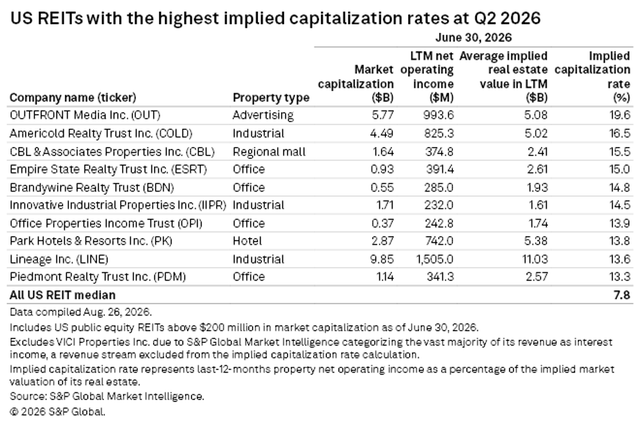
The median REIT implied cap rate as of the end of Q2 was 7.8%. However, many REITs are trading at cap rates far in excess of that, including OUT (19.6%), COLD (16.5%), and CBL & Associates Properties (CBL) (15.5%). Four of the ten highest implied cap rates are Office REITs: Empire State Realty Trust (ESRT) (15%), Brandywine Realty Trust (BDN) (14.8%), Office Properties Income Trust (OPI) (13.9%), and Piedmont Realty Trust (PDM) (13.3%).
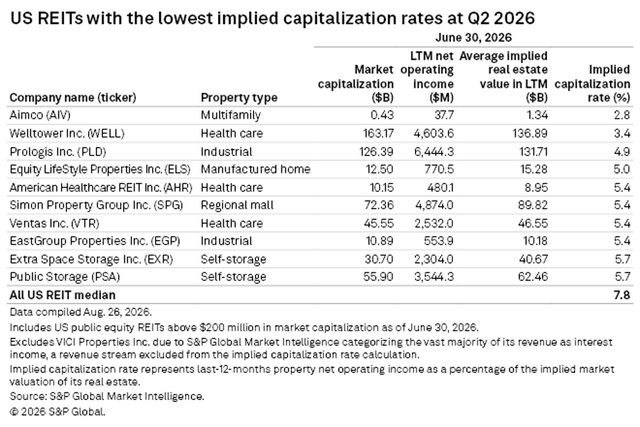
Aimco (AIV) (2.8%) has the lowest implied cap rate in the REIT sector, but that figure is a bit distorted by the fact that Aimco is in the process of liquidating assets and is thus being valued largely on expected liquidation proceeds. The more conventionally valued REITs with the lowest implied cap rates are WELL (3.4%), Prologis (PLD) (4.9%), Equity LifeStyle Properties (ELS) (5.0%), and AHR (5.4%).
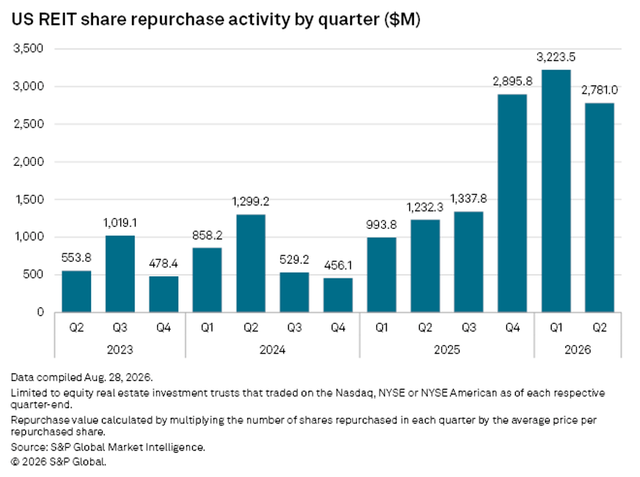
With most REITs trading at elevated implied cap rates and material discounts to NAV, it presents an attractive opportunity to buy back shares well below fair value. If a REIT can sell properties at or above fair value and repurchase shares at an NAV discount, that fuels NAV accretion. If a REIT can sell assets at a cap rate lower than the implied cap rate at which they can buy back their common shares, that too is accretive. For each of the past 3 quarters, REITs have aggressively repurchased shares, including more than $2.78B in Q2 2026 alone.
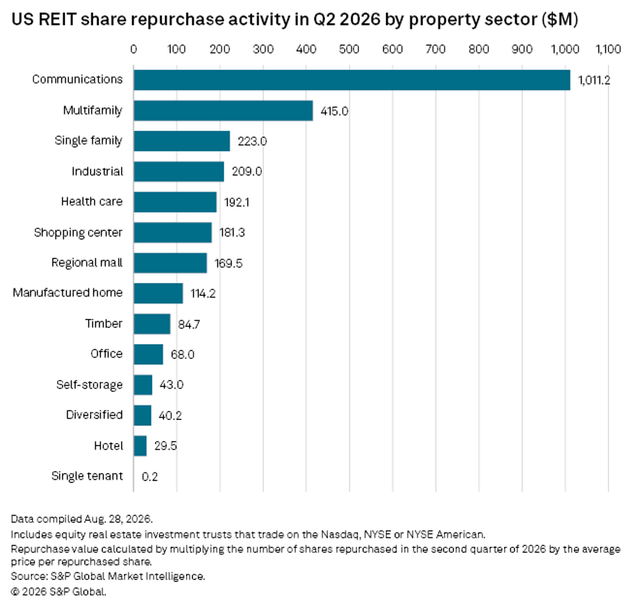
Share repurchases were highest among deeply discounted Communications ($1.01B) and Multifamily ($415M) REITs, where buybacks could be conducted in a highly accretive manner. Other property types that saw heavy share repurchases were Single Family Housing ($223M), Industrial ($209M), and Health Care ($192.1M).
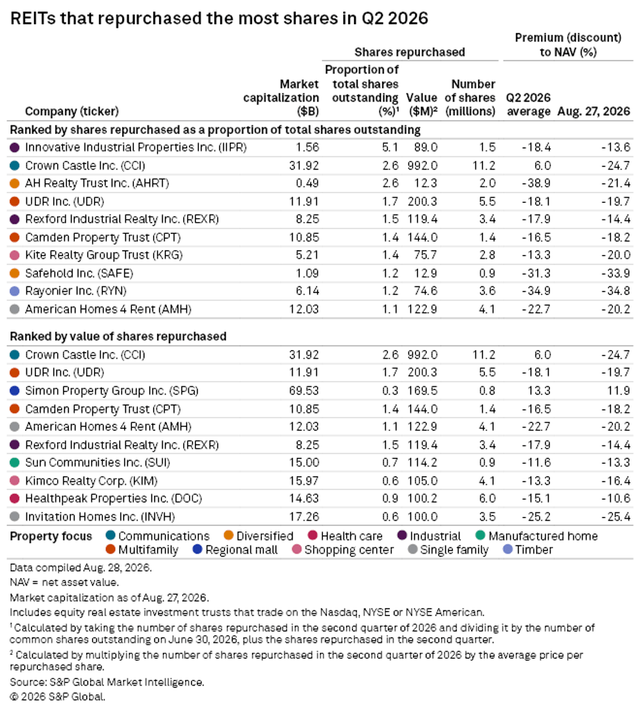
Crown Castle (CCI) repurchased a staggering $992M of shares during Q2, followed by UDR (UDR) with $200.3M, Simon Property Group (SPG) with $169.5M, Camden Property Trust (CPT) with $144M, and American Homes 4 Rent (AMH) with $122.9M. The REITs that repurchased the highest proportion of their total shares outstanding were Innovative Industrial Properties (IIPR) (5.1% of outstanding shares), CCI (2.6%), AHRT (2.6%), UDR (1.7%), and Redford Industrial Realty (REXR) (1.5%).
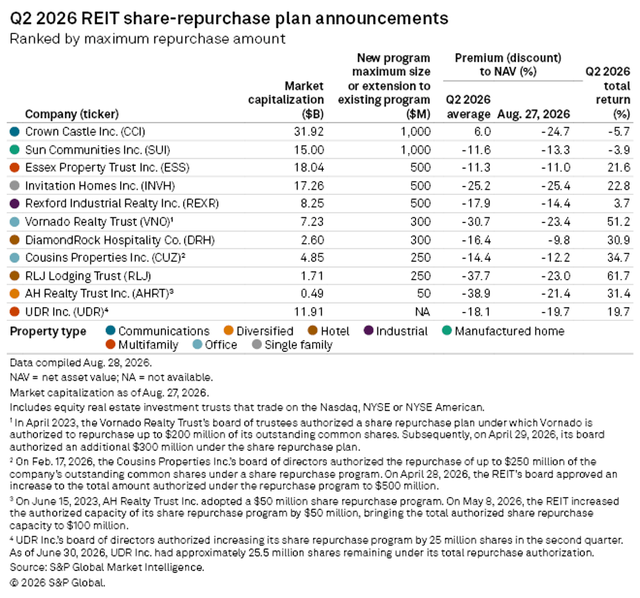
With the exception of CCI and Sun Communities (SUI), the rest of the top ten REITs that announced new share repurchase programs or extensions during Q2 saw strong total returns during the quarter. Six of these REITs saw gains greater than 20%. Many of these REITs still have a significant amount of accretive share repurchases coming through the remainder of the year and more REITs will almost certainly announce new buyback programs or extensions since NAV discounts and elevated implied cap rates remain widespread throughout the REIT sector. With numerous REITs taking prudent action to capitalize on the undervaluation of their shares, REIT investors have the opportunity to potentially reap the benefits as well.
Important Notes and Disclosure
All articles are published and provided as an information source for investors capable of making their own investment decisions. None of the information offered should be construed to be advice or a recommendation that any particular security, portfolio of securities, transaction, or investment strategy is suitable for any specific person. The information offered is impersonal and not tailored to the investment needs of any specific person.
We cannot determine whether the content of any article or recommendation is appropriate for any specific person. Readers should contact their financial professional to discuss the suitability of any of the strategies or holdings before implementation in their portfolio. Research and information are provided for informational purposes only and are not intended for trading purposes. NEVER make an investment decision based solely on the information provided in our articles.
We may hold, purchase, or sell positions in securities mentioned in our articles and will not disclose this information to subscribers, nor the time the positions in the securities were acquired. We may liquidate shares in profiled companies at any time without notice. We may also take positions inconsistent with the information and views expressed on our website.
We routinely own and trade the same securities purchased or sold for advisory clients of 2MCAC. This circumstance is communicated to our clients on an ongoing basis. As fiduciaries, we prioritize our clients’ interests above those of our corporate and personal accounts to avoid conflict and adverse selection in trading these commonly held interests.
Past performance does not guarantee future results. Investing in publicly held securities is speculative and involves risk, including the possible loss of principal. Historical returns should not be used as the primary basis for investment decisions. Although the statements of fact and data in this report have been obtained from sources believed to be reliable, 2MCAC does not guarantee their accuracy and assumes no liability or responsibility for any omissions/errors
Commentary may contain forward-looking statements that are by definition uncertain. Actual results may differ materially from our forecasts or estimations, and 2MCAC and its affiliates cannot be held liable for the use of and reliance upon the opinions, estimates, forecasts, and findings in this article.
Through October 2021, The State of REITs was published exclusively on Seeking Alpha by Simon Bowler, Sector Analyst at 2nd Market Capital Services Corporation (2MCSC). Editions subsequent to October 2021 will be published on this website in addition to other platforms that may include Seeking Alpha. 2MCSC was formed in 1989 and provides investment research and consulting services to 2nd Market Capital Advisory Corporation. 2MCSC does not provide investment advice. 2MCSC is a separate entity but related under common ownership to 2nd Market Capital Advisory (2MCAC), a Wisconsin registered investment advisor. Simon Bowler is an investment advisor representative of 2MCAC. Any positive comments made by others should not be construed as an endorsement of the author's abilities to act as an investment advisor.
S&P disclosure: S&P Global Market Intelligence LLC. Contains copyrighted material distributed under license from S&P.
Discover more from 2nd Market Capital Advisory Corp
Subscribe to get the latest posts sent to your email.